CFC Rules in Ukraine 2026: Who Must File Notices and Reports
Reviews of our Clients
... our work on joint projects assured us of your high level of professionalism
Your foreign company did not enter into a single contract this year, received no income, and carried out no actual business activity. It may seem logical that there is nothing to report.
But this is exactly the assumption that can lead to penalties. The obligation to file a controlled foreign company (CFC) report does not depend on whether the company actually operated—it depends on whether you were its controlling person during the reporting period. Even owning 100% of a dormant company with no transactions does not eliminate the reporting obligation; the report simply reflects zero activity rather than disappearing as a filing requirement.
Another common mistake is to assume that controlling-person status depends only on the size of your ownership interest. In fact, you may not be listed among the company’s shareholders at all and still be treated as its controller if you make the actual decisions—for example, approve transactions, control bank accounts, or select counterparties. The registered shareholder and the person exercising actual control are not always the same.
The absence of income, account activity, or business operations by a foreign company does not by itself release its controlling person from CFC reporting obligations in Ukraine. The scope of the obligations depends primarily on the person’s Ukrainian tax residency, ownership interest in the company, or ability to exercise actual control.
Who Is Treated as a Controlling Person of a CFC?
The analysis should begin with the tax residency of the potential controller. Citizenship alone is not enough to reach this conclusion.
Under Article 39² of the Tax Code of Ukraine, a Ukrainian tax resident may be treated as a controlling person if the resident:
- owns more than 50% of a foreign legal entity;
- owns more than 10% of a foreign legal entity if Ukrainian residents collectively own 50% or more of that entity;
- exercises actual control over a foreign legal entity independently or together with other Ukrainian residents.
For the second criterion, it is necessary to determine not only the person’s own ownership interest but also the composition of the other shareholders and the aggregate interest held by Ukrainian residents. If ownership is held through other companies, the analysis covers the entire corporate chain. Information about the direct shareholder alone may be insufficient.
Actual Control Without an Ownership Interest
A person may be treated as a controlling person even if they are not listed among the company’s shareholders. What matters is whether the person has a real ability to influence the foreign legal entity’s activities.
When assessing actual control, the review may include the authority to give binding instructions to management bodies, approve material transactions, dispose of assets, or conduct transactions through the company’s bank accounts. The key is to establish who actually makes the decisions rather than relying only on the formally appointed director or registered owner.
For example, if the ownership interest is registered in another person’s name but a Ukrainian tax resident determines the counterparties, contract terms, and payment procedures, the existence of actual control should be assessed. The conclusion is based on the overall set of documents, powers, and facts relating to the company’s operations.
You may also find this useful: How to Cease Being a Ukrainian Tax Resident
CFC Notification vs. CFC Report: What Is the Difference?
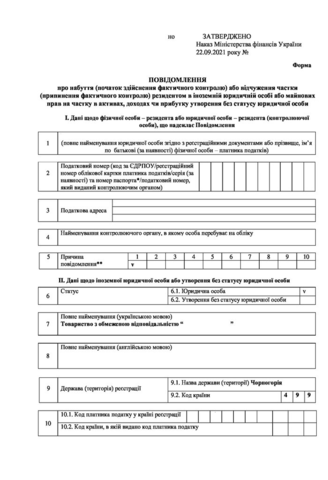
A CFC notification and a CFC report serve different purposes.
A notification relates to an event connected with ownership or control.
A report is filed for the relevant reporting period and contains information about a specific CFC and its financial indicators. Filing one document does not replace the other.
We have explained the difference and the filing rules in more detail here: What Is the Difference Between a CFC Notification and a CFC Report?
Is a CFC Report Required if the Company Did Not Operate or Earn a Profit?
The reporting obligation should be considered separately from the question of tax payment. No transactions, a loss, or an exemption of CFC profit from taxation in Ukraine do not, by themselves, eliminate the controlling person’s obligation to file a CFC report.
My Company Had No Business Activity
If the foreign company entered into no contracts and earned no income during the reporting year, the first question is whether the person was its controlling person during that period. If a reporting obligation exists, the lack of activity is reflected in the relevant financial data.
For example, a Ukrainian tax resident owned 100% of a foreign company throughout 2025. The fact that the company had no transactions is not, by itself, a legal basis for failing to file a CFC report for that year.
My Company Made a Loss or Its Profit Is Exempt From Tax
A loss and an exemption of CFC profit from taxation are legally different. In the first case, the company did not generate profit for the relevant period. In the second, profit may exist, but if the conditions established by the Tax Code are met, it is not included in the controlling person’s taxable income in Ukraine.
In both situations, the obligation to file a CFC report must be determined separately. If a tax exemption applies to the CFC’s profit, the specific legal basis must be verified and documents confirming compliance with its conditions should be prepared.
You may also find this useful: Taxes Paid Abroad by Ukrainian Tax Residents: What Risks Should Ukrainians Consider?
What if the Financial Statements Are Not Ready or the Filing Deadline Has Already Been Missed?
The foreign company’s financial statements may not be ready by the date when the controlling person must report in Ukraine. In that case, the Tax Code provides for a shortened CFC report: it is filed by the annual reporting deadline, followed later by a full report containing the required information and attachments.
If a shortened report for 2025 was filed on time, the full report must be filed by December 31, 2026. A shortened report does not replace the full filing and does not automatically restore a deadline that has already been missed.
What to Do if the Required Documents Were Not Filed
Before preparing any filings, reconstruct the sequence of events:
- Determine the date when the ownership interest was acquired or actual control began.
- Review subsequent changes in ownership, the ownership structure, and the person’s authority in relation to the company.
- Identify the reporting periods during which the person was the controlling person of each CFC.
- Collect corporate documents, financial statements, previously filed notifications, CFC reports, and tax returns.
- Determine which documents still need to be filed and whether the figures in the tax returns also need to be reviewed.
Missing a deadline does not terminate the obligation to file the required documents. Potential liability must be assessed separately, taking into account the type of violation, the date it occurred, and the transitional provisions of the Tax Code governing the CFC rules during martial law. Special provisions on penalties do not cancel the underlying notification and reporting obligations.
You may also find this useful: Foreign Company, Ukrainian Taxes: CFC Rules and Place of Management
How We Help With CFC Compliance in Ukraine
For companies with multiple shareholders, multi-tier ownership structures, or a split between formal and actual authority, the key issue is correctly identifying the controlling person. Once controller status is established, the focus shifts to when the obligations arose, the relevant reporting periods, and whether the financial documentation is complete.
Our lawyers:
- analyze tax residency, the ownership structure, corporate documents, and the actual management of the foreign company;
- determine whether a CFC notification must be filed, which reporting periods require CFC reports, and what supporting documents are needed;
- if the financial statements are not yet ready, assess whether a shortened CFC report can be filed and determine the deadline for the full report;
- if documents were not filed previously, reconstruct the timeline and determine the sequence for completing the outstanding obligations;
- prepare the CFC report and provide filing instructions.
Our focus is on protecting the client: we determine whether a person is a controlling person, assess whether remaining in that position is appropriate, consider the business as a whole, and can help optimize the CFC structure. We are fully transparent with our clients.
If you need help filing a CFC report in Ukraine, contact our specialists now rather than losing more time.
CFC report filing service pricing is available here
Services on the topic of this material
Our publications on this matter
Our clients